Demystifying GST and BAS: A Comprehensive Guide for Business Owners in Australia


GST and BAS for Small Business: An Australian Business Owner's Guide
Understanding your Goods and Services Tax (GST) and Business Activity Statement (BAS) obligations is an important part of running a business in Australia.
Whether you're a sole trader, starting a new business or managing an established company, knowing when to register for GST, what to report and when to lodge your BAS can help you avoid penalties and manage your cash flow.
This guide explains GST and BAS for small business, including registration requirements, GST calculations, reporting methods and BAS lodgement deadlines.
What is GST and how does it work?
Goods and Services Tax (GST) is a broad-based tax of 10% applied to most goods and services sold or consumed in Australia.
Businesses registered for GST generally collect GST from customers when making taxable sales and pay that amount to the Australian Taxation Office (ATO). They can also claim GST credits for the GST included in eligible business purchases and expenses.
For example, if your business sells a product for $1,000 before GST:
- The GST amount is $100.
- The customer pays $1,100, including GST.
- Your business collects the $100 GST and accounts for it through its BAS.
When you purchase goods or services for your business, you may be entitled to claim back the GST included in those purchases.
The difference between the GST collected on sales and the GST credits claimed on purchases determines your net GST position.
What goods and services are GST-free?
Although GST applies to most business transactions, certain goods and services are classified as GST-free.
Common examples include:
- Basic food items, such as bread, milk, fruit and vegetables.
- Certain medical and healthcare services.
- Eligible education and childcare services.
- Some exports of goods and services.
- Certain sales of farmland and precious metals, subject to specific conditions.
Businesses do not charge GST on GST-free sales but can generally claim GST credits on eligible purchases used to make those sales.
What are input-taxed supplies?
Input-taxed supplies are different from GST-free sales.
With input-taxed supplies, businesses do not charge GST and generally cannot claim GST credits for purchases relating to those supplies.
Common examples include financial supplies, such as lending money, and the rental or sale of existing residential property.
Understanding these distinctions is important for accurate GST reporting, particularly for businesses offering a mix of taxable, GST-free and input-taxed goods or services.
When does a small business need to register for GST?
GST registration is compulsory for most Australian businesses once their annual GST turnover reaches $75,000.
The registration requirements are:
- Businesses and sole traders: GST turnover of $75,000 or more.
- Non-profit organisations: GST turnover of $150,000 or more.
- Taxi, limousine and ride-sourcing services: Registration is required regardless of turnover.
- Businesses claiming fuel tax credits: GST registration is required.
Businesses must register within 21 days of becoming aware that they have reached, or are expected to reach, the applicable threshold.
You must have an Australian Business Number (ABN) to register for GST.
How is GST turnover calculated?
GST turnover is based on business income rather than profit.
The ATO considers both your current GST turnover, covering the current month and previous 11 months, and your projected GST turnover, covering the current month and next 11 months.
GST turnover generally includes taxable sales and GST-free sales, but excludes GST included in sales, input-taxed sales and certain other transactions.
Example: GST turnover versus profit
Consider a small business with:
- Annual GST-exclusive sales revenue: $100,000
- Business expenses: $30,000
- Profit before tax: $70,000
Although the business earns a profit of $70,000, its GST turnover is $100,000.
Assuming the sales are included in GST turnover, the business exceeds the $75,000 registration threshold and must register for GST.
The same principle applies to sole traders. Your GST registration obligations are based on turnover, regardless of how much profit you retain.
Can you voluntarily register for GST?
Yes. Businesses with GST turnover below $75,000 can choose to register voluntarily.
Voluntary registration allows businesses to claim GST credits on eligible business purchases. However, once registered, they must generally charge GST on taxable sales and meet the associated GST reporting obligations.
For some businesses, particularly those purchasing significant equipment or supplies, voluntary registration may be beneficial.
For others, the additional reporting requirements may outweigh the benefits. A registered tax agent can help you assess whether voluntary GST registration makes sense for your financial circumstances.
How to register for GST in Australia
You can register for GST through:
- ATO Online services for business, if you already have an ABN.
- The Australian Government Business Registration Service, when registering a new business.
- A registered tax agent who can complete the registration on your behalf.
To access Online services for business, you generally need a Digital ID, such as myID, linked to your business through Relationship Authorisation Manager (RAM).
Once registered, the ATO will confirm your GST registration details and reporting obligations.
The ATO will also make your Business Activity Statement available when it is time to lodge.
How to calculate GST in Australia
GST calculations are relatively straightforward for goods and services subject to the standard 10% rate.
Adding GST to a price
Multiply the GST-exclusive price by 1.1.
For example:
$100 × 1.1 = $110 including GST.
Calculating GST from a GST-inclusive price
Divide the GST-inclusive price by 11.
For example:
$110 ÷ 11 = $10 GST.
These calculations apply to fully taxable sales. GST-free and input-taxed supplies are treated differently.
How to claim GST credits on business expenses
GST-registered businesses can generally claim GST credits for purchases that:
- Are used for business purposes.
- Include GST in the purchase price.
- Are not used to make input-taxed supplies.
- Meet the ATO's record-keeping and documentation requirements.
For purchases costing more than $82.50, including GST, businesses generally need to hold valid tax invoices to claim GST credits.
For example, if your business purchases $1,100 of eligible office equipment, including $100 GST, you may be able to claim that $100 as a GST credit.
Remember that not all business expenses include GST. Employee wages, for example, do not attract GST, so there are no GST credits to claim on wages.
What is a Business Activity Statement (BAS)?
A Business Activity Statement (BAS) is a form used by businesses to report and pay certain tax obligations to the Australian Taxation Office.
GST-registered businesses must generally lodge a BAS monthly or quarterly, unless they are eligible to report GST annually.
A BAS brings together relevant business tax obligations for a reporting period, helping the ATO determine how much a business owes or may be entitled to receive as a credit or refund.
What is included in a BAS?
Depending on your business operations and registrations, a BAS may include:
- GST: GST collected on taxable sales and GST credits claimed on eligible purchases.
- PAYG withholding: Tax withheld from employee wages and certain other payments.
- PAYG instalments: Payments towards expected income tax liabilities.
- Fringe Benefits Tax (FBT) instalments: Applicable to businesses with relevant FBT obligations.
- Fuel tax credits: Credits available for eligible fuel use.
- Luxury Car Tax (LCT): Applicable to certain sales and imports of luxury vehicles.
- Wine Equalisation Tax (WET): Applicable to certain wine-related transactions.
Not every business needs to report every tax type.
For example, a sole trader without employees may only need to report GST and any applicable PAYG instalments, while a business employing staff may also need to report PAYG withholding.
How is the GST amount on a BAS calculated?
For GST purposes, your BAS generally accounts for the GST collected on taxable sales, less the GST credits available on eligible business purchases.
Consider a business that makes the following transactions during a quarter:

In this example, the business owes $3,000 in GST for the quarter.
This assumes all sales are fully taxable, all purchases qualify for GST credits and there are no GST adjustments.
The business's final BAS payment may differ if it also has PAYG withholding, PAYG instalments or other tax obligations.
For most small businesses with GST turnover below $10 million, the ATO's Simpler BAS method requires three main GST figures:
- G1: Total sales
- 1A: GST on sales
- 1B: GST on purchases
These BAS figures are used to calculate the business's GST liability or credit for the reporting period.
Cash versus accrual accounting for GST
The GST accounting method your business uses determines when you report GST on sales and when you can claim GST credits on purchases.
There are two main methods, being cash accounting and non-cash accounting, commonly called accrual accounting.
Cash accounting for GST
Under the cash method, businesses report GST when payment is received from customers and generally claim GST credits when eligible purchases are paid for.
For example, if you issue a tax invoice on 30 June but your customer pays on 15 July, the GST on that sale is reported in the period covering July.
This method can make cash flow management easier because GST liabilities are more closely aligned with money received.
Businesses with aggregated turnover below $10 million can generally choose to account for GST on a cash basis. Other eligibility rules also apply.
Accrual accounting for GST
Under the non-cash or accrual method, GST is generally attributed to the earlier of receiving payment or issuing an invoice.
For example, if you issue an invoice on 30 June and receive payment on 15 July, the GST is generally reported in the period ending 30 June.
This means a business may need to pay GST before receiving payment from its customer.
Accrual accounting can create additional cash flow pressure for businesses with longer customer payment terms.
Most larger businesses use non-cash GST accounting, although specific exceptions can apply.
Which GST accounting method should you use?
The right method depends on your business size, eligibility, customer payment terms and financial circumstances.
It's also important to understand that the GST accounting method and the accounting method used for income tax are separate considerations.
How often do businesses need to lodge a BAS?
Your GST reporting cycle generally depends on your GST turnover and any reporting requirements set by the ATO.
Quarterly BAS reporting
Most small businesses with GST turnover below $20 million report and pay GST quarterly, unless they have chosen or been directed to report monthly.
The standard quarterly BAS due dates are:
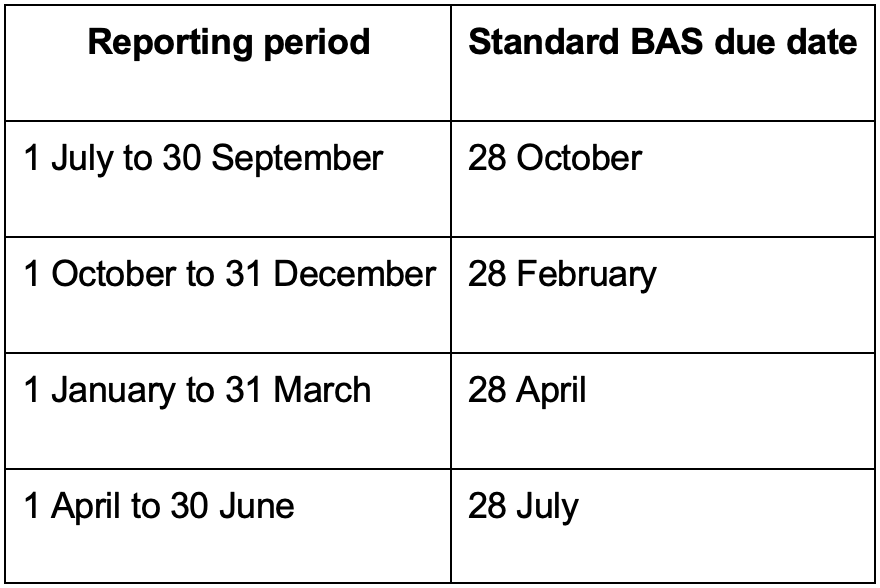
Businesses lodging their quarterly BAS online may qualify for an additional two weeks for certain quarters.
A registered tax or BAS agent may also be able to access different lodgement deadlines for eligible clients.
Always check the due date shown on your activity statement or in ATO Online services.
Monthly BAS reporting
Businesses with GST turnover of $20 million or more must generally report monthly and lodge online.
Smaller businesses can also choose monthly GST reporting.
Monthly BAS lodgement and payment obligations are generally due on the 21st day of the following month.
For example, a BAS covering September is generally due on 21 October.
Some businesses prefer monthly reporting because it spreads their GST payment obligations across the year rather than accumulating larger quarterly amounts.
Annual GST reporting
Eligible businesses that voluntarily register for GST and remain below the compulsory registration threshold may choose to report and pay GST annually.
The standard annual GST return due date is 31 October. However, if you are not required to lodge an income tax return, the due date is generally 28 February following the reporting year. Different deadlines can apply when using a registered agent.
Annual GST reporting uses an annual GST return rather than the usual quarterly BAS reporting cycle.
Businesses should confirm their eligibility before changing their reporting arrangements.
How to prepare and lodge your BAS
Accurate BAS preparation begins with maintaining reliable records of your business transactions throughout the reporting period.
Here are the main steps involved.
1. Reconcile your business transactions
Check that your accounting software reflects the transactions for the correct period.
This includes reconciling bank statements, customer payments, supplier invoices and other business expenses.
Ensure all relevant transactions have been recorded and categorised correctly.
2. Check your GST calculations
Review taxable sales, GST-free transactions and input-taxed supplies to confirm they have been treated correctly.
Check that GST amounts on purchases are accurate and supported by valid tax invoices where required.
3. Review your payroll and other tax obligations
If your business employs staff, check PAYG withholding amounts against payroll software and payroll records.
Also review any PAYG instalments, fringe benefits tax instalments or other amounts that need to be included in your BAS.
4. Prepare your BAS figures
Use your accounting software or bookkeeping records to calculate the figures required for the BAS form.
Businesses using integrated accounting software can often generate BAS reports directly from their financial records, reducing manual calculations and the risk of errors.
Review the figures before submitting them.
5. Lodge your BAS and arrange payment
You can lodge your BAS through several channels:
- ATO Online services: Prepare and lodge your BAS online through the ATO's business services.
- Accounting software: Some Standard Business Reporting (SBR)-enabled software allows businesses to submit BAS information directly to the ATO.
- Registered tax or BAS agent: An agent can prepare and lodge your BAS on your behalf.
- Mail: Where paper lodgement is available, use the original BAS form supplied by the ATO and the pre-addressed envelope provided.
Most businesses find online BAS lodgement more convenient, particularly when using accounting software that keeps financial records up to date.
You can also review your activity statements and payment obligations through the ATO website.
Tips for keeping your GST and BAS obligations on track
Good record keeping helps small business owners meet their tax obligations while maintaining a clearer picture of their financial position.
Keep accurate records
The ATO generally requires businesses to keep GST-related records for at least five years, although some records may need to be retained longer.
This includes tax invoices, business expense records, bank statements and documents supporting GST calculations.
Use accounting software consistently
Accounting software can help you track business purchases, categorise transactions and calculate GST amounts.
For businesses with employees, integrating payroll software can also make it easier to reconcile PAYG withholding and prepare accurate BAS figures.
However, automated calculations still need to be reviewed.
Plan for upcoming GST payments
GST collected from customers forms part of a business's cash flow until it becomes payable to the ATO.
It's important to understand your likely GST liability ahead of each BAS due date so you can plan for upcoming payment obligations.
Regularly reviewing your GST position alongside your broader cash flow forecast can help you anticipate payments and make informed decisions about working capital.
Review your cash flow before BAS deadlines
Regularly reviewing your cash flow can help you prepare for quarterly BAS payments, especially if your business experiences seasonal revenue or delayed customer payments.
If you're concerned about your ability to pay your BAS, seek professional advice or contact the ATO before the due date.
Lodge your BAS on time
Late BAS lodgement can result in failure-to-lodge penalties, while overdue tax payments can attract interest charges.
Meeting your reporting and payment obligations helps avoid additional costs.
GST and BAS FAQs
Do I need to register for GST if my turnover is under $75,000?
Generally, no. GST registration is optional if your GST turnover is below $75,000, unless you provide taxi or ride-sourcing services or need to register to claim fuel tax credits.
You can register voluntarily, but doing so means you must meet GST reporting obligations.
Do sole traders need to lodge a BAS?
Sole traders registered for GST generally need to lodge a BAS monthly or quarterly, unless eligible to report GST annually.
Sole traders who are not GST-registered may still have activity statement obligations for other taxes, such as PAYG instalments.
Can I lodge my own BAS?
Yes. Business owners can prepare and lodge their own BAS through ATO online services or compatible accounting software.
However, a registered tax or BAS agent can assist with BAS preparation, checking GST calculations and meeting lodgement requirements.
What happens if I have no sales during a BAS period?
GST-registered businesses generally still need to lodge a BAS even if they have nothing to report.
This is called a nil BAS.
You can lodge a nil BAS online or through the ATO's automated phone service on 13 72 26, where eligible.
Can I claim GST credits on all business purchases?
No. You can generally only claim GST credits where the purchase includes GST and is eligible for a credit.
Expenses such as employee wages and purchases from suppliers who are not registered for GST do not normally include claimable GST.
Purchases used for private purposes or making input-taxed supplies may also be ineligible.
What happens if I miss a BAS due date?
The ATO may apply late-lodgement penalties or interest charges where relevant payment obligations remain outstanding.
If you've missed a deadline, lodge your BAS as soon as possible and contact the ATO or your accountant if you need help.
What's the difference between GST and BAS?
GST is the 10% tax applied to most goods and services sold in Australia.
A BAS is the reporting form businesses use to declare GST amounts and other applicable tax obligations to the ATO.
What is the difference between GST-free and input-taxed sales?
Both types of sales generally have no GST charged to customers.
However, businesses can generally claim GST credits on eligible purchases related to GST-free sales, while input-taxed sales generally do not allow those credits.
Can my accountant lodge my BAS for me?
Yes. A registered tax agent or BAS agent can prepare and lodge your BAS on your behalf.
Working with an accountant can also help ensure your GST reporting, business records and payment obligations are managed correctly.
Need help with GST or BAS?
Understanding your GST and BAS obligations is important, but keeping on top of reporting requirements can be time-consuming, particularly as your business grows.
At Bonerath, we help Australian business owners manage GST registration, BAS preparation and lodgement, bookkeeping and ongoing tax compliance.
Whether you're registering for GST for the first time, reviewing your reporting method or looking for support with your regular BAS obligations, our team can help.
Get in touch with Bonerath to discuss your business accounting needs.